When's each person's PTO topped up?

 3:42
"When's each person's PTO topped up?"
Each employer can select between three options for when their people's "PTO balance available" is automatically topped up.
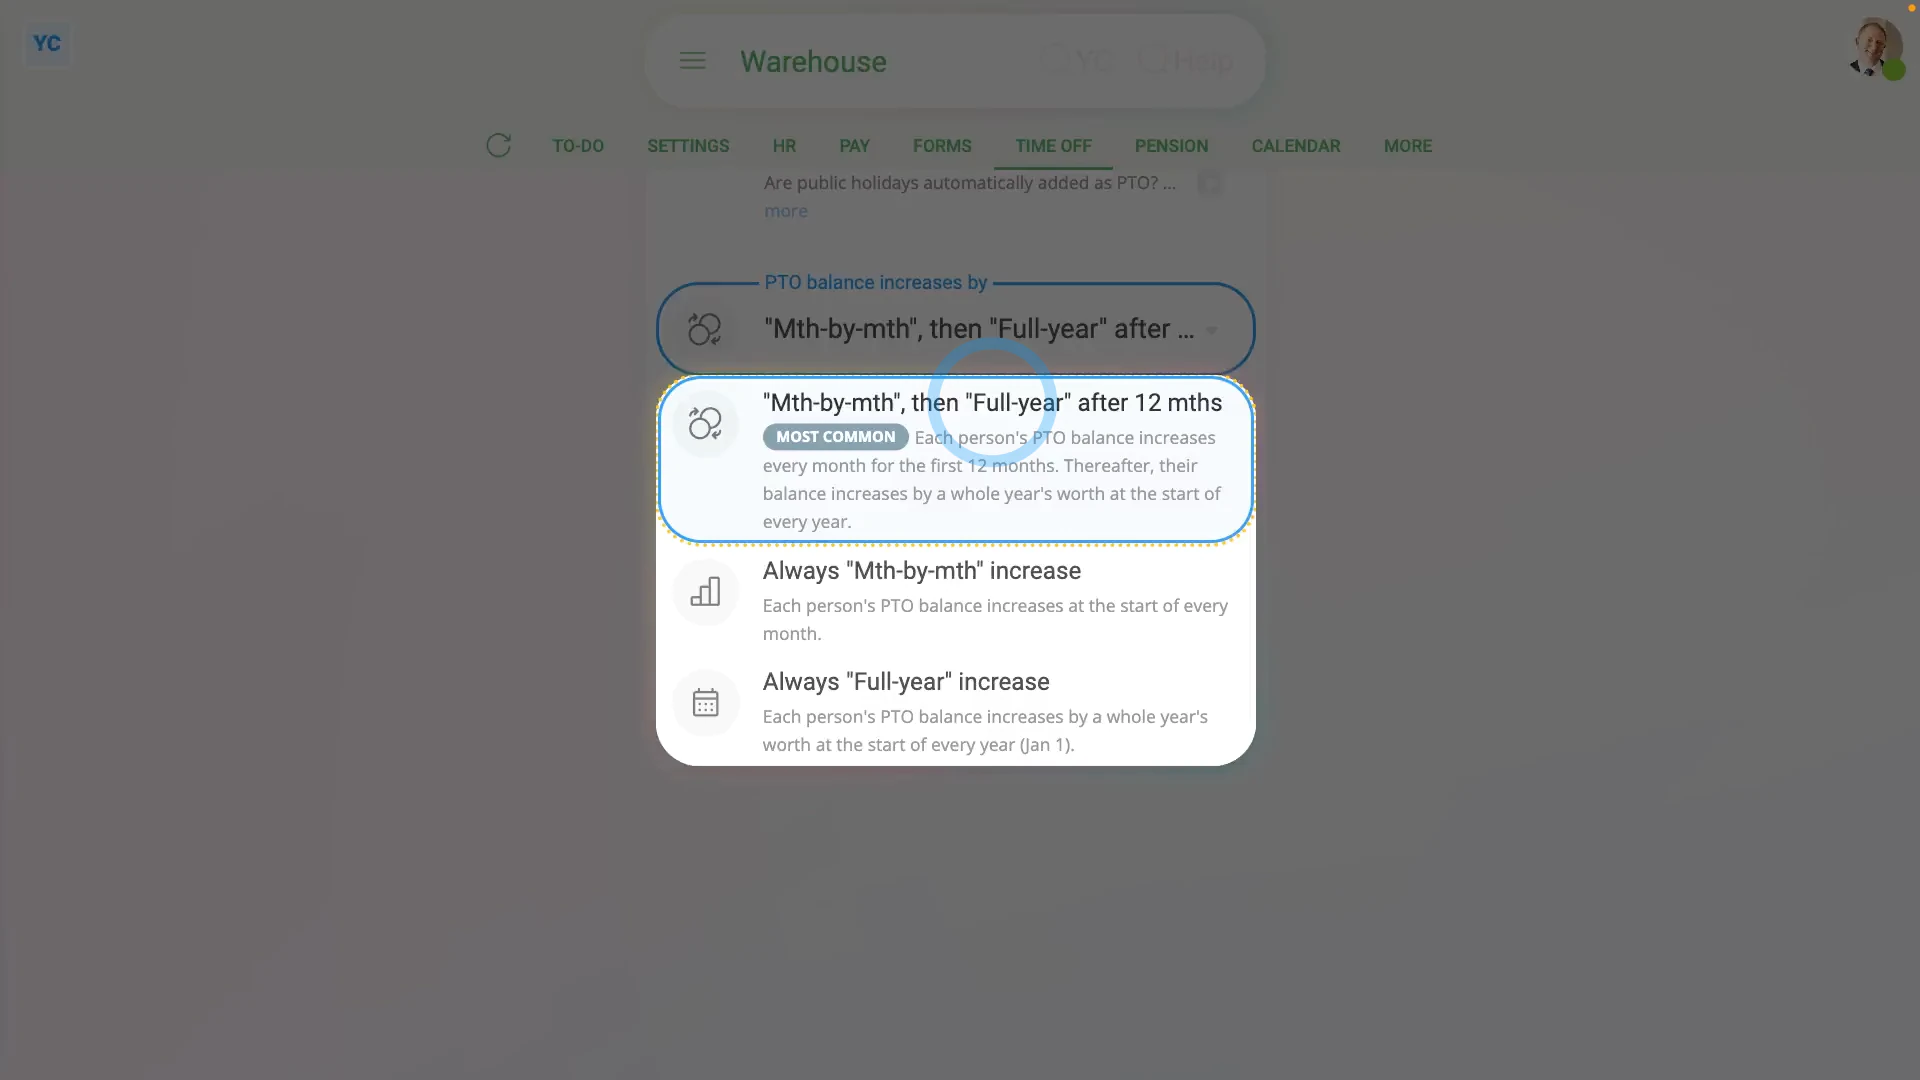
To set when your people's "PTO balance available" is automatically topped up:
- First, select the payroll group on: "Menu", then "Payroll groups"
- Then tap: "Time off", then "Time off settings"
- Keep in mind that the payroll group's "Do "PTO top up" on" option only shows if you've selected the "Limited PTO" option.
- Next, scroll down to the "Advanced" heading, and tap: "Do "PTO top up" on"
- The "Always "Full-year" top up" option:
Is the most generous option, where each existing person gets 12 months worth of yearly "PTO top up" every January 1st. - And newly hired people also get a yearly "PTO top up", on their first day. The yearly "PTO top up" covers whatever months remain, from their join date, right through until December 31st.
- The disadvantage, however, is that any new hire that joins in January now has 12 months of "PTO balance available" that can immediately be approved.
- In other words, the new hire could've been employed by you for only one month, but could've had 12 months worth of PTO approved.
- Some people call it "allowing a negative PTO balance", which isn't recommended for new hires.
- The "Always "Mth-by-mth" top up" option:
Is the strictest option, where every person, including new hires and existing employees, all only get their "PTO top up" added one-month at a time. - Each monthly "PTO top up" is always auto-added on the 1st of every month.
- The disadvantage, however, is that sometimes you may want to offer your existing people more flexibility.
- You may have people, who've gained your trust by working for more than 12 months. You may want them to be free to consume their future top-ups earlier in the year.
- For example, the trusted employee may want to take two weeks off in the middle of the year, or when the weather's nice. The trusted employee would then take less time off when it's the end of the year.
- The lack of flexibility of month-by-month top-ups isn't recommended for your trusted existing employees.
- The ""Mth-by-mth", then "Full-year" after 12 mths" option:
Is the most common option. - It gives you the strictness of month-by-month top-ups during each person's first 12 months.
- Then as soon as the person hits their 12-month anniversary, it automatically switches them to a yearly "PTO top up". The yearly "PTO top up" would be for whatever months remain in the year, until December 31st.
- And from then on, the person continues to receive a 12-month yearly "PTO top up" every January 1st.
- And finally, many employers find ""Mth-by-mth", then "Full-year" after 12 mths" to be the "Goldilocks" option. Not too generous, and not too strict.

Keep in mind that:
- No matter which option you select, when a person's employment's ending, 1st Money always does its best to reclaim any outstanding: "PTO balance available"
- Where possible, outstanding PTO balances are automatically reclaimed during the calculation of a person's final pay.
To learn more:
- About reclaiming outstanding "PTO balance available" on final pay, watch the video on: PTO settlement at termination
 PTO settlement at termination
And that's it! That's everything you need to know about all three options for when each person's PTO is topped up!
www.1st.money/uk/help/Time_Off/When's_each_person's_PTO_topped_up